In its November 18, 2026 market report, PANews described a Bitcoin sell-off that had shifted attention from the price decline itself to whether buyers could absorb supply around $62,000–$66,000. Bitcoin had fallen to about $61,000 on November 15, a four-month low, before rebounding toward $66,000. The report said buying had not yet shown sustained strength.
The cost-basis evidence is mixed. Glassnode identified the $62,000–$66,000 range, near the August low, as a concentration of short-term holders’ acquisition costs. It estimated that roughly one-fifth of short-term holders’ positions lay in that range and that buyers acquired about 66,000 BTC there during the two sharpest days of selling. CryptoQuant data, as cited by PANews, indicated that long-term holders sold heavily between $62,000 and $65,000 while new buyers took the other side. Those observations show turnover at the price band, not that it will hold as support.
The report also cited analyst Darkfost’s calculation that, excluding coins held for more than 10 years, 46% of circulating supply was in profit; at $62,000, the share fell to 37.8%. That exclusion matters: the figures should not be read as the profitability rate for all circulating Bitcoin or as a count of profitable holders. PANews did not specify the measurement date or underlying dataset for those percentages.
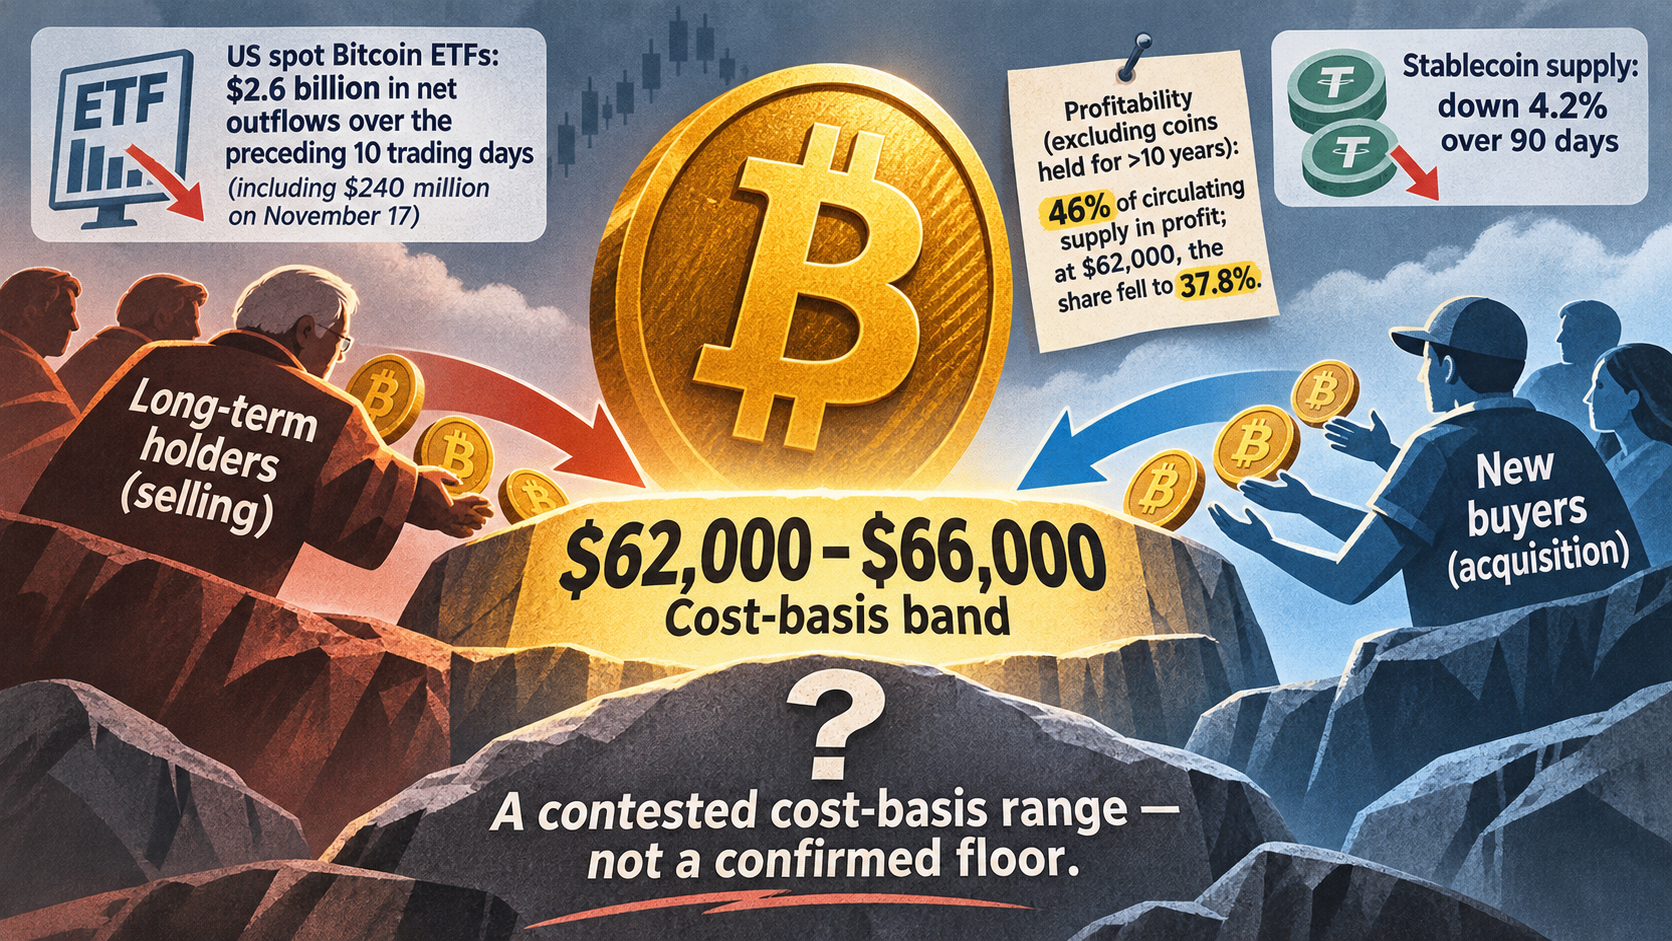
Flows offered another test of demand. PANews reported $2.6 billion in net outflows from US spot Bitcoin ETFs over the preceding 10 trading days, including $240 million on November 17. It also reported a 4.2% decline in stablecoin supply over 90 days, without identifying the dataset or measurement endpoints. Neither measure alone establishes how much buying capacity was available at a particular Bitcoin price.
The $62,000–$66,000 zone is therefore a contested cost-basis range, not a confirmed floor. The reported acquisition and selling activity establishes its relevance; whether incoming demand can continue to absorb sales remained unresolved in the November 18 report.